Your Retirement Paycheck.
A free email course for Waco pre-retirees and recent retirees. Learn how to turn savings into a paycheck, when to claim Social Security, and how to keep taxes from eating into it.
Start the Course.
Use the email address where you get The Waco Buzz. Your welcome email from Chad arrives in about 5 minutes.
Starting a course also subscribes you to The Waco Buzz, Waco's free local newsletter, if you aren't already. Unsubscribe anytime.
Last email's big point
- Your income gap is monthly spending minus guaranteed income, and 25 times the annual gap is a rough savings target.
Today's key takeaways
- If you were born in 1960 or later, claiming at 62 pays 70% of your full benefit; waiting until 70 pays 124%.
- For one person, waiting pays off if you live past your early 80s.
- For married couples, that breakeven age is only half the question.
Hi there,
For many Waco households, Social Security is the largest guaranteed income they'll ever have. You can start it as early as 62 or as late as 70, and the age you pick sets the size of your check for life, adjusted each year for inflation.
How your check changes with claiming age
Full retirement age is 67 for anyone born in 1960 or later. Claim before then and your benefit is reduced; wait past it and it grows 8% a year until 70. Here's Gary, who retires next year after 28 years at the plant. His full benefit is $2,600 a month:
| Gary claims at | Share of full benefit | Monthly check |
|---|---|---|
| 62 | 70% | $1,820 |
| 67 | 100% | $2,600 |
| 70 | 124% | $3,224 |
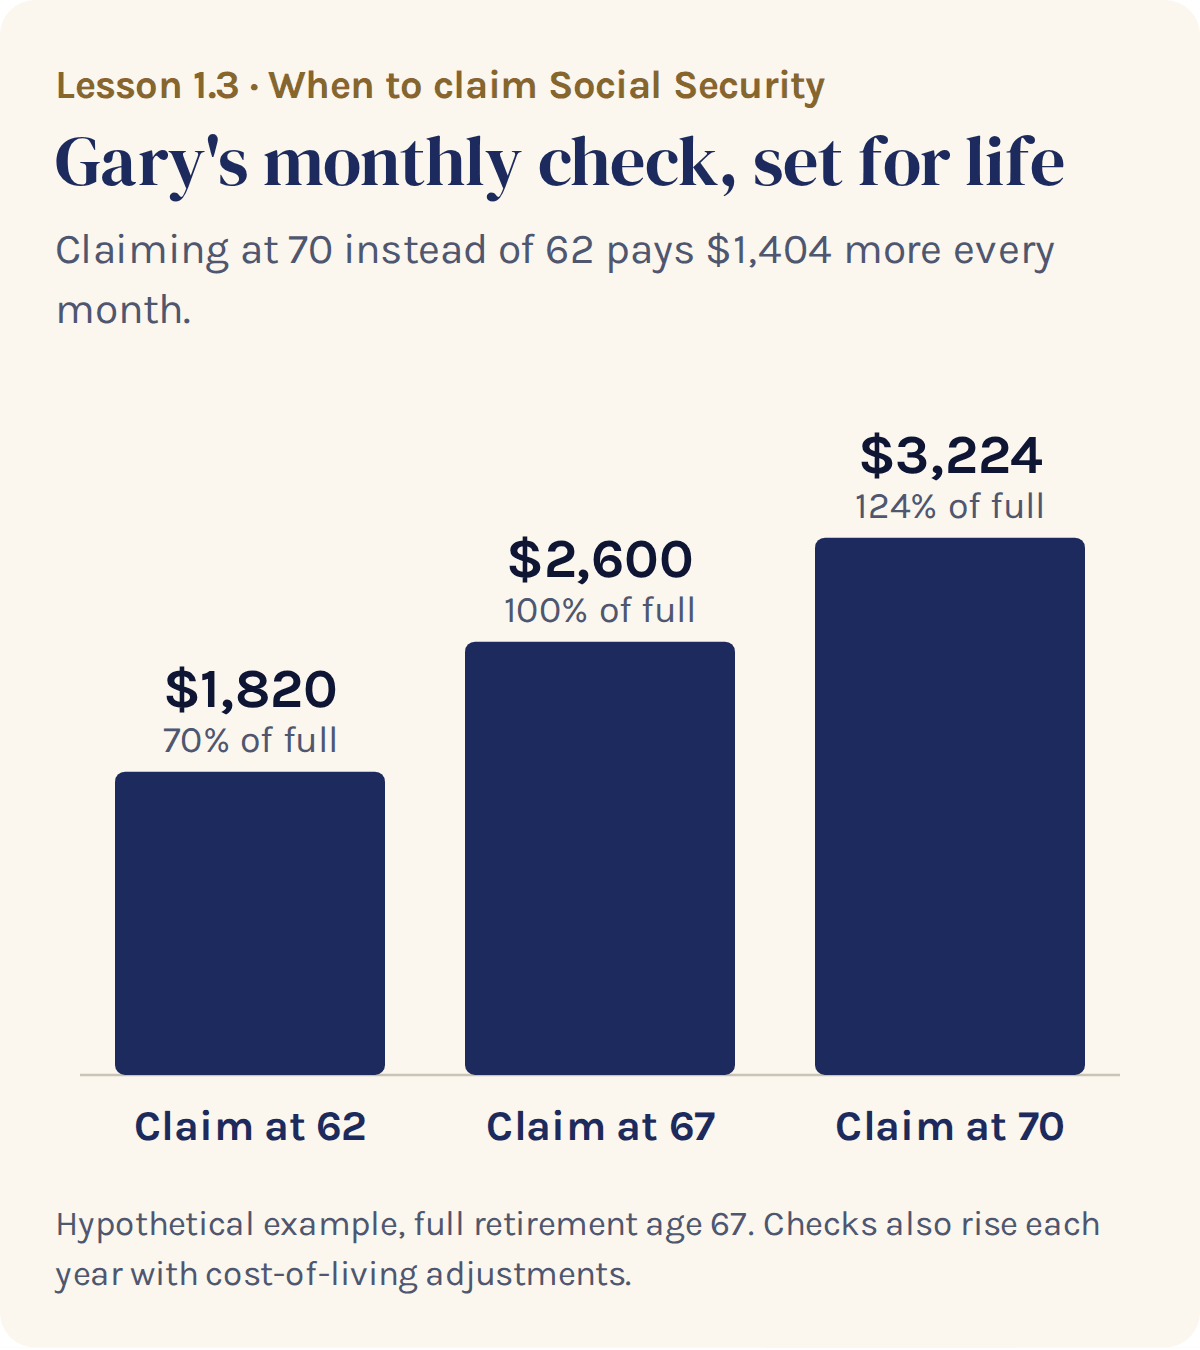
That's $1,404 a month between his earliest and latest option, for as long as he lives.
One note on your own statement: its estimates assume you keep earning at your current pay until you claim. If you stop earlier, your benefit can come in a little lower.
When waiting to claim pays off
If Gary claims at 70 instead of 67, he gives up three years of checks, then collects $624 more every month. Ignoring inflation adjustments and taxes, the larger checks catch up around age 82½. Comparing 62 with 67, they catch up around 79.
Breakeven is a fair question, but it treats claiming as a bet on one person's lifespan. For a married couple, the bigger question is about the second lifespan, because when one spouse dies, one of the two checks stops. Which one keeps coming depends on what the higher earner decided years earlier. That's the next email.
Three more Social Security rules to know
- Retiring and claiming are separate decisions. Gary can retire at 65 and claim at 67 or 70 if savings cover the years in between.
- Claiming early while still earning. Before full retirement age, Social Security holds back $1 of benefits for every $2 you earn above $24,480 (in 2026). You get it back later through a higher check.
- Medicare still starts at 65, even if you delay Social Security.
Chad
A full lesson from the course. Scroll to read it.