How to turn what you've saved into a monthly paycheck, which account to draw from and in what order, when to file for Social Security, what a bad market costs once you're withdrawing, and more. Taught by Chad Castle, RICP®, ChFC®, and Jessica Burch, MBA, CFP®. $29 per person.
Tell us where to send the dates for the next workshop, and we'll email you as soon as they're set.
Put money in, leave it alone, add more when you can.
Retirement is a different ball game. Which account to draw from, and in what order? When to file for Social Security, and what that does to the spouse who outlives you? What does a bad market cost when you're withdrawing, not saving?
Done right, the answers are what let you actually spend what you saved, instead of worrying or guarding it.
Nobody hands you those answers on your last day of work. So every quarter since 2012, we have spent two evenings addressing these questions in a classroom at MCC.
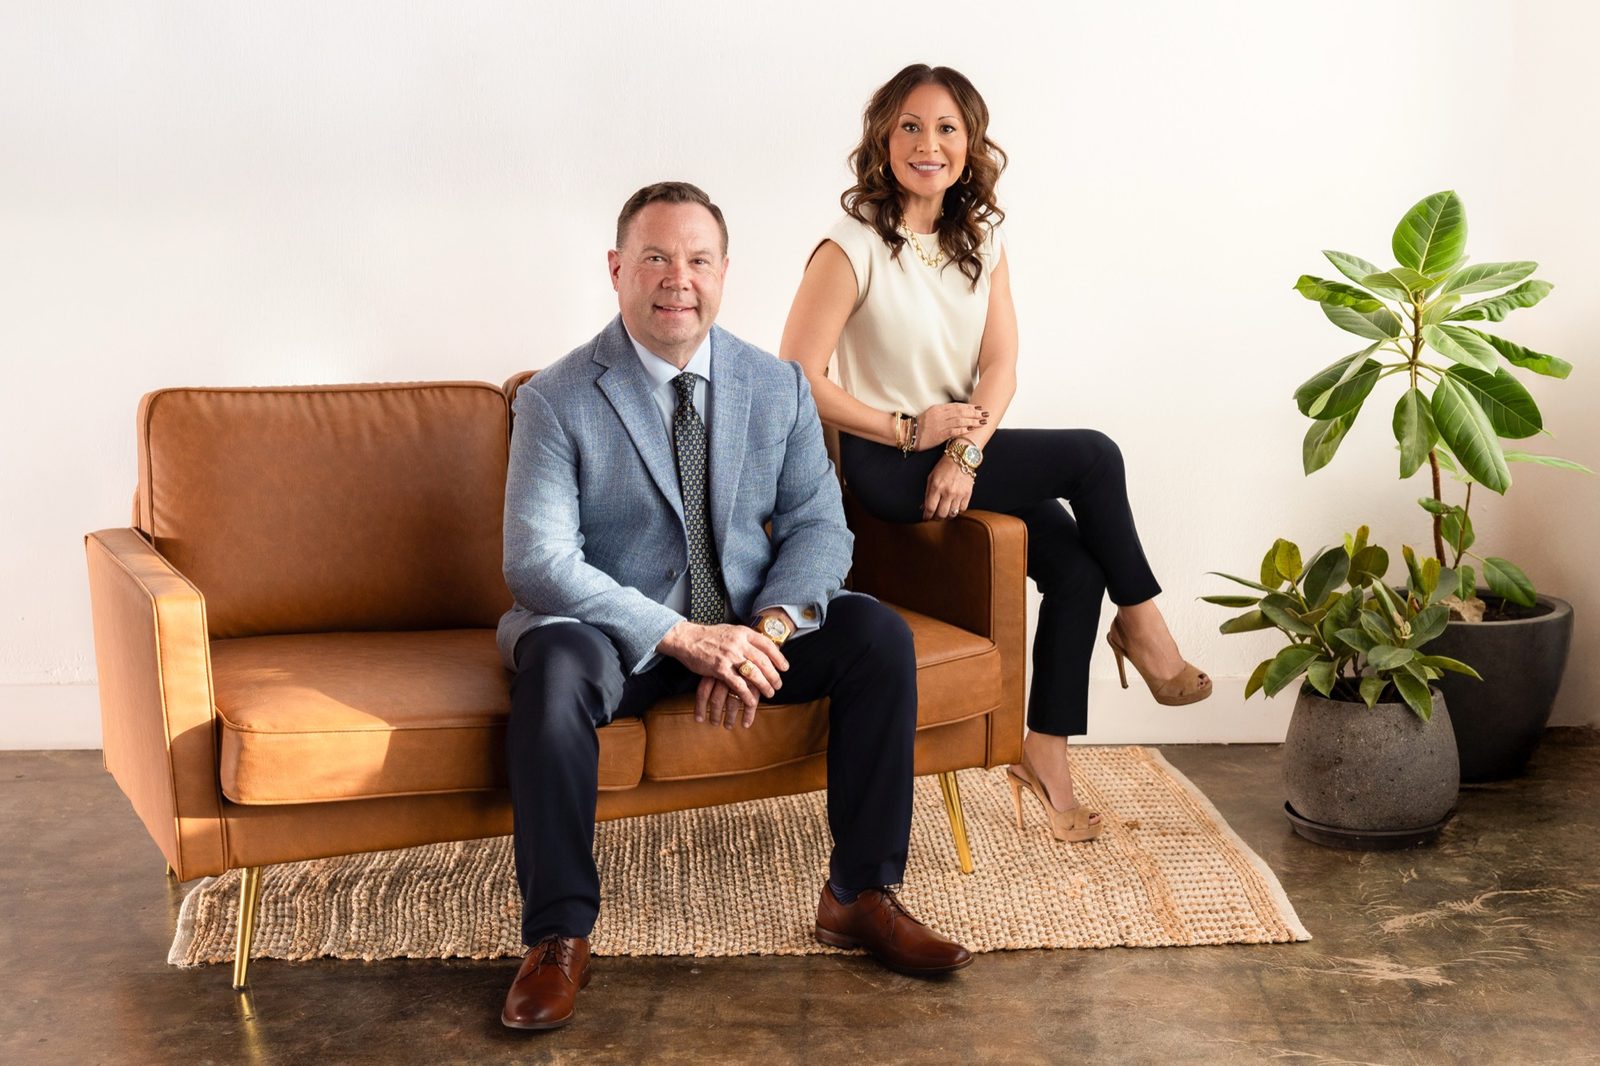
Chad Castle, RICP®, ChFC® and Jessica Burch, MBA, CFP®
Co-Founders, Winnacle Wealth
Cash flow, income, taxes, protection, estate, and markets. Six areas, one connected plan, plus time for the questions you bring.
Every dollar gets a job before you spend it. Income, raises, and bonuses go into one account first, and your checking holds only what you've planned to spend that month.
Turn your savings and Social Security into a monthly paycheck. When to claim benefits, and how to take income from the portfolio: an insured or pension-based source, a conservative withdrawal rate, or a market-based approach. The goal is income that doesn't run out before you do.
Which accounts to spend first, how much of your Social Security is taxable, when a Roth conversion pays off, using QCDs to give from your IRA, and staying under the brackets that cost you. Small moves across the years that decide how much you keep.
What your spouse would lose in income if you died, and what a few years of long-term care would cost if you needed it. How to measure both risks, and the insurance and other tools for covering them.
Wills, trusts, powers of attorney, and the beneficiary forms that override your will. What you need in place, and how to spare your family probate and guesswork.
Markets have historically rewarded investors who stay in and leave the money alone. Set your risk by the return your plan actually needs, then choose how to invest: buy, hold, and rebalance; dividends; equity-income; or more conservative fixed positions.
November 2 and 9
Mondays, 6:00–8:30 PM · MAC Building, Room 111
$29 per person covers both nights. If your spouse is coming, register them too.
Register at MCC →
You'll land on the college's continuing-education catalog under Personal Finance. Look for Retire Ready and pick your dates.
The college will ask you to create an account. The fee is $29 per person, so if your spouse is coming, register them too.
MCC sends your confirmation. Then a few notes from us before class: a welcome from Chad and Jessica, what to expect on Monday night, and a reminder the morning of each night.
Registration is handled by McLennan Community College. You don't have to be an MCC student, and there's no application. Nothing to bring but yourself.
No. MCC charges per person, so each of you registers for $29. You'll sit together, and each of you gets a workbook.
There's no minimum. The information is relevant to any pre- or current retiree.
Plenty of attendees do. The workshop is about asking better questions of whoever advises you.
Plan on both if you can. MCC's continuing education office handles roster changes.