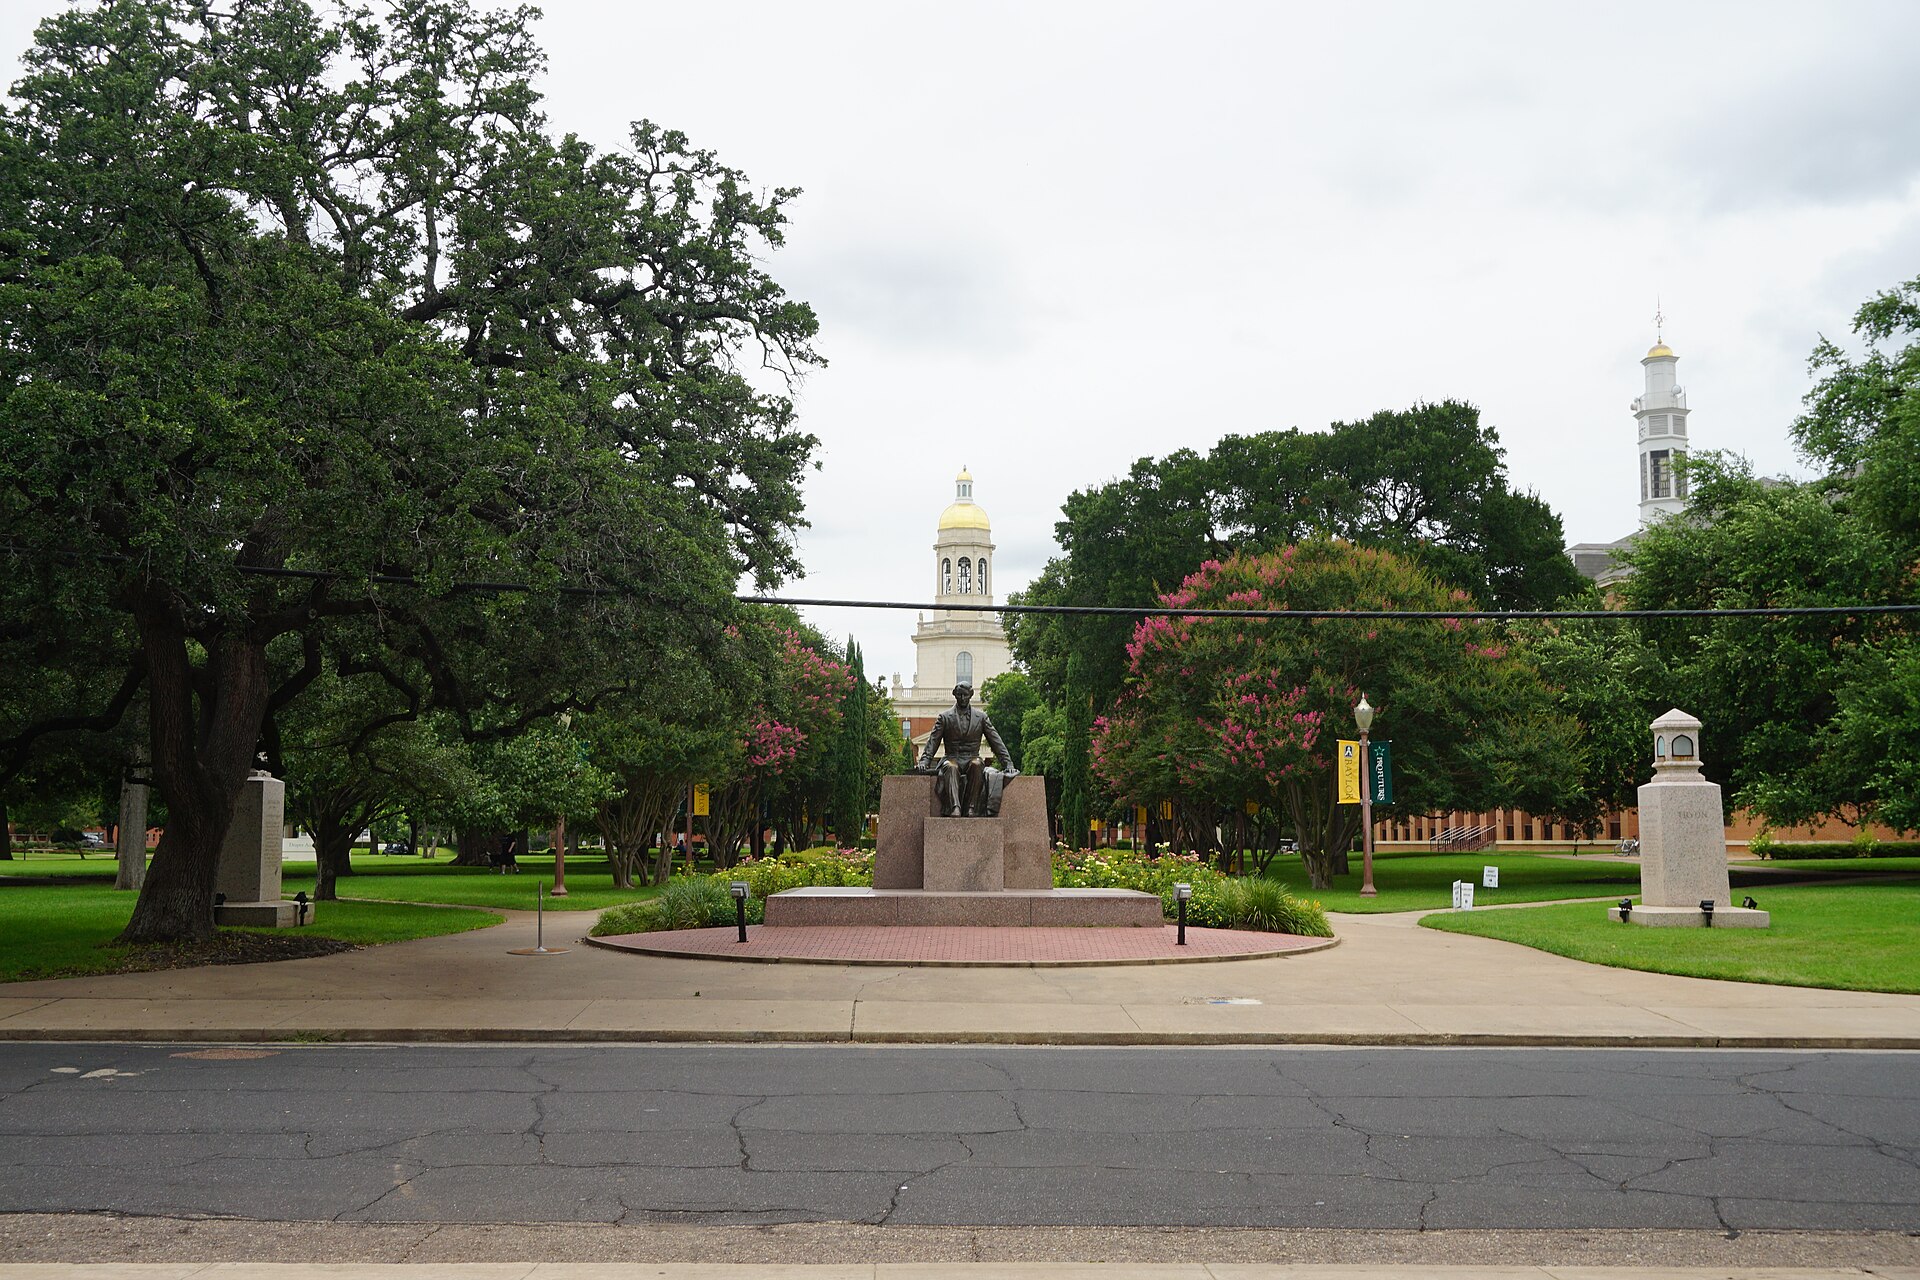
Founders Mall and Pat Neff Hall at Baylor University in Waco, Texas

Retire From Baylor With a Plan for What’s Next.


You’ve built savings and benefits through your work at Baylor. Now you want to know when you can retire and how to responsibly use what you’ve earned. Winnacle Wealth helps bring your benefits, retirement income, and taxes together into a simple and sustainable plan.

Independent fiduciary financial planning in Waco, Texas. Talk Through Your Retirement

Cover of the guide Baylor University Retirement Guide

Baylor University Retirement Guide

Planning guide · updated for 2026

  • Retirement eligibility and coverage checks
  • How 403(b) and 457(b) choices differ
  • Payout decisions to review before you leave

Before You Set a Retirement Date.


Your account balance doesn’t tell you which benefits continue when you leave. Check how your departure date and payout choices would affect the money your household has to spend.

1

Saving Without a Retirement Target

Baylor’s contribution and your own savings need to support your household’s goals. Review what you’re setting aside against the retirement income you expect to need, rather than assuming the default election is enough.

2

Letting a Payout Set Your Tax Bill

A 457(b) payout can arrive alongside salary or other taxable income. Review the payment timing and form before leaving to avoid an unexpected tax bill.

3

Leaving Before You Check Retiree Benefits

Baylor’s retiree categories have different eligibility tests and benefits. Confirm which category applies to your planned departure and what health coverage you would need to arrange yourself.

4

Overlooking a Benefit Your Family Uses

If a spouse or child uses tuition remission, include it in your retirement planning. Ask HR how your departure would affect eligibility before committing to a date.

Build Your Retirement Plan With Winnacle.


Your Baylor accounts are part of your household’s retirement picture. We consider them alongside your other savings and the people who depend on you. Our One-Page Plan puts your priorities in view and identifies the next decision to address.

  1. Start With Your Life After Work

    We work through the spending your plan needs to support, including family commitments and the things you want more time for.

  2. Compare the Choices Available to You

    We compare your savings and payout choices with attention to the income left after taxes. Baylor HR and TIAA confirm plan eligibility and the terms that apply to your accounts.

  3. Put the Next Steps in Writing

    We identify what needs a decision now and what can wait. When a question needs your tax professional or HR office, we help you prepare for that conversation.

Meet Your Advisors

Chad Castle, RICP®, ChFC®

Chad Castle, RICP®, ChFC®

Co-founder. Serving families in financial services since 1995.

Jessica Burch, MBA, CFP®

Jessica Burch, MBA, CFP®

Co-founder. Helps clients with retirement planning, tax planning, and major life transitions.

Baylor Contribution Calculator


Compare a full year at each contribution rate using 2026 IRS limits. This annualized illustration does not calculate actual 2026 payroll contributions: the 8% rate began August 1.

Your inputs

Assumptions

Texas has no state income tax, so there are no state inputs. Federal income tax on the contributions is not shown.

What the numbers show

Baylor at 8% (annualized)$0
Your annual deferral (capped)$0
Annualized difference from 10.8%$0
403(b) annual allowance unused$0
457(b) annual allowance unused$0

Enter your numbers to see the stack.

This tool is educational and simplified. It compares a full year at each contribution rate using your salary and 2026 limits, not your actual 2026 payroll. It ignores differences in eligible pay, when contributions start, savings in other plans, special catch-up contributions, loans, investment growth and taxes. Available contribution room may exceed what fits your budget. Confirm your amounts with Baylor or TIAA. Results are simplified estimates, depend on assumptions entered by the user, and do not predict actual tax consequences. It is not tax or investment advice. Talk to your advisor and tax professional before making any election.

Your Baylor Benefits at a Glance.


Use this overview as a reference while you review your retirement options. The guide covers the rules and questions in more detail.

The Baylor Retirement Plan is a 403(b) at TIAA with separate employer and employee accounts. The 457(b), retiree insurance, and tuition benefits have their own eligibility and election rules.

Baylor's 403(b) contribution

8% since August 1, 2026, for eligible employees, subject to the plan’s pay definition and $360,000 compensation cap for 2026. No employee contribution is required. Eligibility generally starts at age 21 with a year of service; contributions are fully vested.

Your own 403(b) deferrals

$24,500 in 2026, plus $8,000 at ages 50–59 or 64+, or $11,250 instead at ages 60–63. Pre-tax or Roth deferrals are available to eligible nonstudent employees from hire. New hires since June 2024 default to 3% unless changed.

The Baylor 457(b)

A separate pre-tax plan with a 2026 limit generally equal to the lesser of $24,500 or includible compensation, and no age-based catch-up (50+ or 60–63). It is unfunded: participants are unsecured creditors and plan assets remain subject to Baylor’s creditors.

Retiree benefits

Retiree I generally requires age 55 and ten continuous full-time years, subject to HR’s policy review. HRA funding and tuition benefits depend on category and enrollment. Retiree dental and vision require prior employee enrollment; cancellation is permanent.

Tuition remission

Eligible full-time employees receive 100% tuition remission after one year, for up to two courses and eight hours per semester. Family benefits follow service and hire-date schedules, with program restrictions. Family graduate remission is taxable.

Insurance and the HSA

Eligible full-time employees receive employer-paid life coverage of $50,000–$100,000. LTD generally pays 60% of monthly earnings up to $15,000 after a 90-day elimination period, subject to offsets and policy terms. Check the applicable plan-year guide for HSA funding.
Baylor Retirement Questions.


How much does Baylor contribute to my 403(b)?

For eligible employees, 8% of plan-eligible pay since August 1, 2026, up to the $360,000 compensation cap for 2026. The contribution is discretionary and pre-tax; it goes into an employer account separate from your own deferrals.

Do I have to contribute to get Baylor's 8%?

No. Eligible employees receive it without making their own deferral. New hires since June 1, 2024 default to a 3% pre-tax employee contribution, with 60 days to choose another rate or opt out.

When does Baylor's contribution start?

Generally at age 21 after one year of service, meaning 1,000 hours in your first year or a later calendar year. Qualifying prior university service can count if HR receives certification within 30 days of hire. Your own deferrals can begin at hire.

403(b) or 457(b): which should I use?

Compare the 403(b)’s age-based catch-ups with the 457(b)’s separate contribution limit, unfunded creditor risk and payout rules. Limits depend on compensation and other-plan contributions. The right mix depends on your tax situation and when you expect to need the money.

What happens to my 457(b) when I leave Baylor?

Your payout election controls when payments start and whether you receive a lump sum, periodic payments, or both. Payments start 60 days after separation unless Baylor receives a later-start election within that window; without a timely payment election, the default is a lump sum. Confirm deadlines with HR; payments are generally taxable when received.

What counts as retiring from Baylor?

Retiree I generally requires age 55 and ten continuous full-time years. Honorary and grandfathered categories have different service tests and benefits. HR determines your category; involuntary termination is excluded and temporary service does not count.

Can I keep my health insurance when I retire?

Active medical ends at month-end. Eligible Retiree I and grandfathered retirees must opt into HRA funding; Honorary Retirees do not receive it. At 65+, annual funding is $2,640 for Retiree I or $3,900 for grandfathered retirees, with qualifying Medicare coverage through Via Benefits required. Before 65, funding varies by covered family members. Benefits can change.

Does the 15-year catch-up apply to me?

Some 403(b) plans let employees with 15 years at a qualifying organization add up to $3,000 a year, with a $15,000 lifetime cap. We did not find this provision in the Baylor documents reviewed. HR or TIAA must confirm whether the plan offers it before you count on extra contributions.

Where can I get help with Baylor retirement questions?

Winnacle Wealth is based at 200 W State Hwy 6, Suite 330, in Waco, Texas. Baylor also provides access to CAPTRUST and TIAA advice on the plan’s investment choices at no additional cost.

Cover of the guide Baylor University Retirement Guide

Baylor University Retirement Guide

Planning guide · updated for 2026

Get the guide ↑

Talk Through Your Plans Before You Leave Baylor.


Bring the decision you’re weighing, whether it’s choosing a date or deciding how to use your savings. A Right Fit Call is a chance to discuss what you need and whether Winnacle’s approach fits.